Intel is reducing the cost to produce its core nodes, directly decreasing the price floor of future CPUs and also stabilizing supply for the data center market. They've seen a 15% and 40% decrease in production costs for Intel 3 and Intel 18A respectively since Q1. It's relevant for the reader because it means high performance silicon will have a lower cost to produce, which could potentially lead to a more value proposition in future client and server products.
Intel 18A yields improve significantly, reducing production costs by 40% and increasing revenue share for 18A-based client CPUs to one-third.
This is due to yield improvements and optimized fabrication process at Intel's advanced nodes. Dave Zinsner, Intel's CFO, stated that yields on Intel 18A saw double digit percentage improvements in the 3rd quarter. This has already started to have an effect on the revenue mix, with 18A based client CPUs now accounting for roughly 1/3rd of all client CPU revenue.
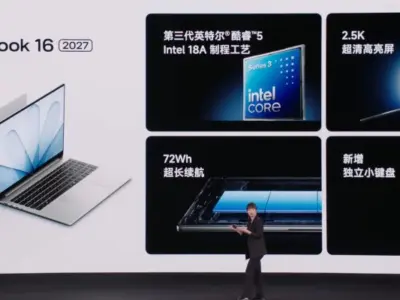
This is up from less than 5% earlier this year. Intel also saw a 70% QoQ increase in shipments for Wildcat Lake. All of their secured supply for Wildcat Lake is already sold out.
Intel is actively adapting production capacity to address the strong demand in server processors. CEO Lip-Bu Tan stated that they've now reached revenue generating shipments for Clearwater Forest, the first server CPU on Intel 18A. They're also re-allocating some production capacity in Oregon to switch from Intel 18A to Intel 3 to serve the needs of the data center.
However, they are having substrate constraints as an issue. They are also adjusting the roadmap to use Intel 18A-P on Diamond Rapids in 2027 and Intel 14A for Coral Rapids in 2028.
Product development is faster than expected for clients, specifically next-gen Core products. Nova Lake, the first client product on Intel 18A-P is seeing development progress faster than planned. During our coverage of the last update for Intel 18A, there were a lot of the same "balance and stability" factors that we discussed here.
But what we're seeing now are the actual cost savings and yield improvements as proof for their roadmap. It is clear that Intel is making the successful shift to more efficient nodes in their manufacturing base.
Intel has confirmed the cost savings and yield improvements are resulting in revenue growth for clients and server products. Shipments of Clearwater Forest are underway. Acceleration of development for Nova Lake (18A-P node).
Continued optimization of Oregon facilities to accommodate the needs of the data center. Substrate constraints.
40% cost reduction is massive for a new node.
Does the 70% QoQ surge in Wildcat Lake shipments indicate strong enterprise adoption or just backlog clearance?
The article notes all secured supply is already sold out. That points to genuine demand rather than just clearing old inventory.
Moving Oregon capacity from 18A to Intel 3 for data center needs sounds like a pragmatic pivot.