
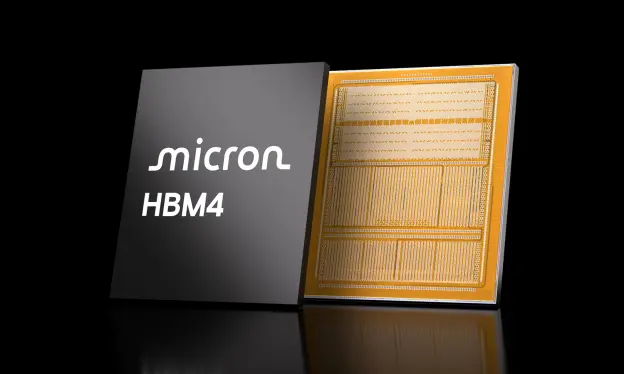
Micron reports its fiscal 2026 third-quarter earnings on September 30, 2026, marking a period of intense financial growth for the memory manufacturer. This update matters to buyers and investors because the company is navigating a critical transition in high-bandwidth memory production while facing scrutiny over long-term contract structures. The results will clarify whether Micron can sustain its current margin trajectory against competitors who are also expanding their AI memory capabilities.
Memory giant reports record margins and expands HBM4 production capacity for AI demand
The company reported a 74% year-over-year revenue increase to $41.46 billion in the third quarter, driven by strong demand for its memory products. Net income under GAAP standards doubled to $28.24 billion during the same period. Non-GAAP gross margins reached a record 84.9%, reflecting the pricing power Micron has maintained in the enterprise and AI sectors.
- FY2026 Q3 Revenue: $41.46 billion
- FY2026 Q3 Net Income (GAAP): $28.24 billion
- FY2026 Q3 Gross Margin (Non-GAAP): 84.9%
- FY2026 Q4 Revenue Forecast: $50.42 billion
- FY2026 Q4 Gross Margin Forecast: 87.3%
Looking ahead, Wall Street forecasts a significant jump in the fourth quarter with revenue expected to reach $50.42 billion. Goldman Sachs projects the non-GAAP gross margin will climb to 87.3% in Q4. The company has already shipped over $1 billion worth of HBM4 memory and plans to increase production capacity by adding up to 60,000 wafers per month by the end of the year.
Micron has announced 16 strategic customer agreements (SCAs) to lock in long-term supply deals with major cloud providers. This number lags behind competitors Samsung and SK Hynix, who have secured more extensive contracts in the same period. Analysts note that these agreements may cap price increases if market rates continue to rise, potentially limiting future margin growth in the second half of 2027.
We looked at Samsung HBM4E Yield Hits 70% as earlier while tracking Micron launches. The upcoming earnings report will serve as a key indicator of how well Micron is executing its capacity expansion plans relative to its peers. Investors will watch closely to see if the company can close the gap in long-term contract volume while maintaining its high-margin position.
Discussion
0 comments
Log in to join the thread with a thoughtful take, question, or correction.